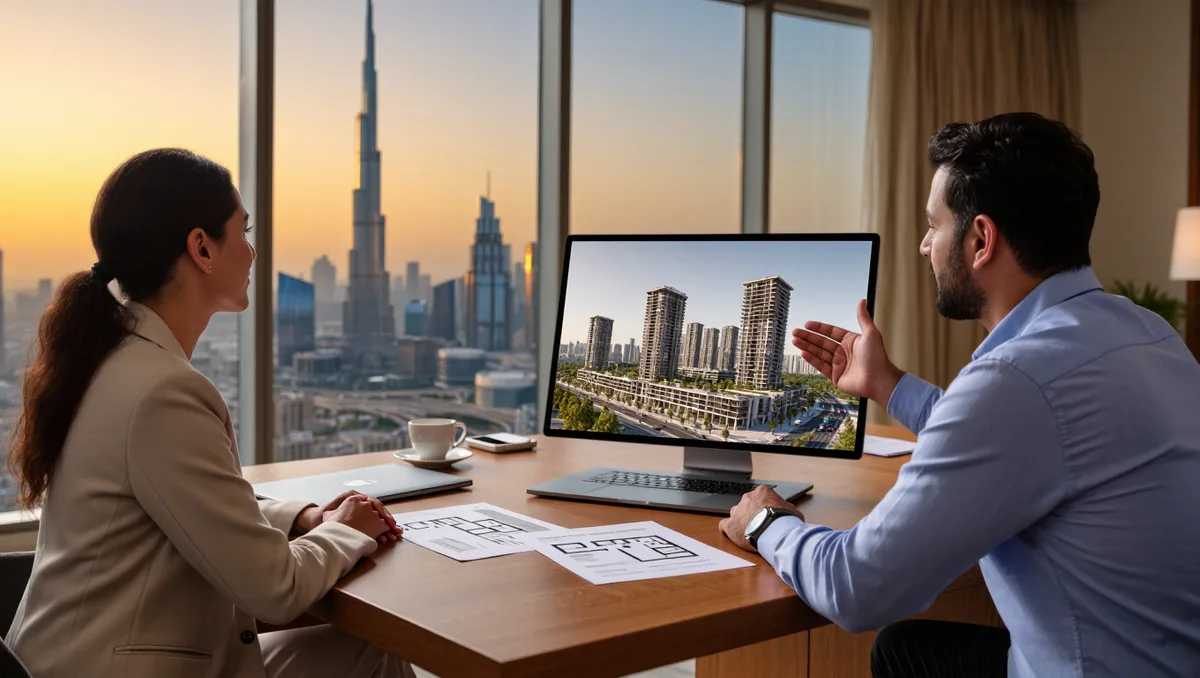
Dubai's property market runs on three things an outsider rarely hears about at a sales launch: off-plan contracts, escrow protection, and a rental system where yields matter more than capital growth. Most homes sold in the city are sold before they exist. The buyer pays in instalments, the developer builds, and a government escrow account holds the money until construction stages are verified.
The market is large enough that this machinery matters beyond the city. Dubai is the most populous city in the United Arab Emirates, with a population of about 4 million as of 2025, and roughly 92 percent of residents are expatriates, according to Wikipedia's Dubai entry. A renter-heavy, investor-heavy city produces a market built for turnover rather than long-term occupation, and that shapes every rule below.
This guide walks through how a transaction actually closes: what off-plan means, what escrow does and does not protect, how a completed sale transfers, and how rental yields are calculated. For broader coverage of the region's property sector, see the real-estate desk.
What does "off-plan" actually mean in Dubai?
Off-plan means buying a property from its plans, before construction is finished, directly from the developer. The buyer signs a sale and purchase agreement, then pays the price in staged instalments tied to construction progress. Payment schedules vary by project; some developers front-load the payments, others stretch them past handover.
The appeal is straightforward: an entry price below completed stock, and a payment plan spread over years instead of one lump sum or a mortgage. The trade-off is equally plain. The buyer carries completion risk, handover timing can slip, and the delivered unit may differ in finish from the marketing material. Resale before handover is possible in many projects but depends on the developer's terms and any transfer fees the contract sets.
For a step-by-step treatment of the buying process itself, the separate guide on how to buy off-plan property in Dubai covers the sequence in detail.
How does escrow protect an off-plan buyer?
Escrow is a bank account controlled by a third party, not the developer. In Dubai's off-plan system, buyer instalments go into a project-specific escrow account, and the developer can only draw funds against verified construction progress. The intent is simple: if a project stalls, the money paid so far is not sitting in the developer's general operating account.
What escrow does not do is guarantee completion. It protects the funds from being diverted; it does not insure the buyer against a project that never finishes or finishes late. Buyers who want a read on a developer's track record look at delivery history across past projects, not at the escrow certificate itself. The escrow framework also applies to registered projects rather than to every informal resale or sub-lease arrangement, so the protection attaches to the specific project registration.
One practical consequence: because draws are progress-linked, a developer's marketing timeline and its construction timeline are two different documents. The second one, verified through the escrow mechanism, is the one that determines when instalments fall due.
What happens when a completed property changes hands?
A completed sale closes at the Dubai Land Department, which registers the transfer and issues a new title deed in the buyer's name. The transfer involves government fees, agent commission if an agent acted, and often a mortgage discharge if the seller had financing. The separate breakdown of Dubai Land Department fees and what a transfer actually costs sets out the line items.
Ownership itself is zoned. Foreign nationals may hold title in designated freehold areas, while ownership rules elsewhere differ. The same zoning logic applies across the Gulf in different forms; Abu Dhabi's arrangements are covered in the explainer on Abu Dhabi's freehold zones.
Two signals matter at the closing stage. First, the title search: confirming the seller actually holds clean title and that no undisclosed mortgage sits against the unit. Second, the handover condition: service charges, outstanding dues and the state of the property itself. A transfer can be registered while a service-charge debt survives it, so the settlement of dues belongs in the contract, not after it.
How do rental yields work, and why do they drive the market?
A rental yield is annual rent divided by the property's price, expressed as a percentage. It answers a different question than capital growth: not "will this unit be worth more later" but "what does it earn while I hold it." In a city where roughly nine in ten residents rent, per the expatriate share documented above, the rental side of the market is the larger and steadier one.
Rents in Dubai are regulated through a registration and index system. Tenancy contracts are registered, and a rental index caps how much an existing rent can be raised at renewal. The mechanics are set out in the guide to how Dubai's rental index caps increases. For investors, the practical effect is that in-unit rent growth is bounded, so the yield case rests on the entry price rather than on aggressive annual increases.
Yield comparisons also depend on how the unit is let. A long-term tenancy and a short-stay letting produce different gross income, different operating costs and different regulatory obligations; the holiday-home variant is covered in the piece on how much a Dubai holiday home can earn. Gross yield and net yield diverge here more than in most markets, because service charges, furnishing and management fees all come out before the net figure. We covered a connected angle in How much can a Dubai holiday home earn.
What this means for an outside buyer
Our analysis of the market's structure comes down to one tension: the same features that make Dubai accessible to outside capital — staged off-plan payments, a fast transfer desk, a large rental base — also shift risk onto the buyer in ways mature markets spread across institutions. Off-plan shifts completion risk to the purchaser. Escrow narrows but does not erase it. Yield-driven pricing rewards buying well over buying often.
The market's scale supports the machinery. Dubai's economy centres on trade, tourism, aviation, financial services and real estate, and the city's rapid construction since the 1990s has produced one of the world's densest skylines, per the Dubai reference material. Volume is the point: a market built for turnover needs clear transfer rules, and it has them.
What the sources above do not establish is any current price level, yield figure or project-specific status, and this guide deliberately makes no claim about them. Anyone pricing a specific transaction needs dated figures from the exchange of title records and the developer's own contract, not from general guides. The broader Gulf context — from Saudi homeownership programs to Omani investment titles — is covered across the markets and finance and property desks.
Where Dubai fits in the wider Gulf market
Dubai is the region's most liquid residential market, but it is not the only model. Saudi Arabia runs a state-backed homeownership program aimed at citizens rather than foreign investors. Oman opens property ownership to foreigners through integrated tourism complexes. Qatar built a rental market from scratch in Lusail. Each answers the same question — who is allowed to own, and how — with different rules.
For an outsider, the useful comparison is not which market is better but which risk each one assigns to the buyer. Dubai assigns completion risk in off-plan deals and price risk everywhere. The escrow system, the transfer desk and the rental index are the three levers that keep that assignment workable. Everything else in the market — the launches, the payment plans, the yield talk — is downstream of those three.